

As the financial results have come out from the major suppliers of server components, we are getting a sense – finally – of how much larger demand is than supply. And in Nvidia’s discussion of its second quarter of fiscal 2026 results, Nvidia gave us some hints in its fiscal 2027 and 2028 years for everyone to contemplate and build their models.
Back in April, when Intel reported its financial results for the first quarter of this year, the company said that the supply shortfall for its overall CPU business was a number that started with a “B,” and that implies to us that the Xeon server CPU shortage was at least 20 percent and probably more like 25 percent. We think that given the superior price/performance that AMD is offering with its current Epyc line that its over-demand might be even higher, perhaps 30 percent and growing as agentic AI takes hold and we see a resurgence in CPU capacity in the AI datacenter. Various OEMs have hinted that their demand is between 25 percent to 30 percent higher than supply as well in their most recent quarters.
With fiscal 2027 components long since allocated to OEMs and ODMs and very likely the majority of components expected to be sold in fiscal 2028 also allocated, Nvidia knows. It doesn’t have to guess. But Nvidia is not required to be explicit when forecasting the future, even though On a call going over the Nvidia numbers for Q2 F2027, chief financial officer Collette Kress did not mince words, telling Wall Street that the company had enough component supplies to grow the datacenter business by slightly more than 70 percent in fiscal 2028.
Later in the call, when asked for what revenues would look like in an unconstrained supply environment, co-founder and chief executive officer Jensen Huang pointed out that Nvidia was on track to double revenues in fiscal 2027 and implied that it might have been able to do that in fiscal 2028 were it not for shortages in DRAM, HBM, flash, and other components. Assume, then, Nvidia could have doubled sales again in F2028 as it will do in F2027. Then the demand would be just under 40 percent larger than the supply. It seems likely that Nvidia’s demand in F2027 is on par with what Intel and the server makers are seeing and what AMD is only speaking broadly about, and that is because Nvidia is such a large part of their businesses.
“The unconstrained would be a lot higher,” Huang said when pressed about the gap. “We will grow 100 percent year over year this year. The unconstrained, you know, is significant, and so we are just going to have to go work hard to get more capacity. And you know we have a large supply chain, we have a really gigantic supply chain, and so we have incredible partners, and we have secured a lot of supply. But we just need a lot more.”
To that end, the commentary provided by Kress along with the Q2 F2027 numbers said that the purchase commitments made by Nvidia are now $279 billion, up 2.3X from the $119 billion it secured through the end of Q1 F2027. These supply commitments span the remainder of 2027 out through fiscal 2029, with a tiny bit allocated for fiscal 2030 and beyond. It is reasonable to expect for purchase commitments to grow to cover the $1 trillion in sales for Grace-Hopper NVL72 and Vera-Rubin NVL72 systems across fiscal 2027 (maybe $365 billion) and 2028 (maybe $625 billion) that Nvidia has penciled into its order books.
And if supply suddenly becomes less constrained – or Nvidia tries to scale back DRAM and HBM memory in its GPUs, CPUs, and DPUs to sell more units – these numbers can be higher.
With that, let’s drill down into the numbers.
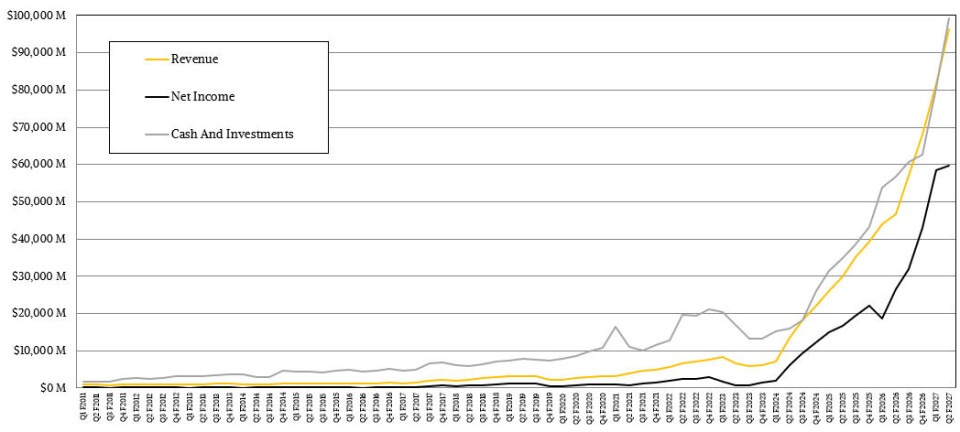
In the July quarter, Nvidia nearly hit $100 billion in overall sales, which is amazing considering where the company was in the established HPC and emerging AI markets a decade ago, when sales were two orders of magnitude smaller.
To be precise, which we like around here at The Next Platform, sales in the quarter were up 105.9 percent to $96.22 billion, driven by and large by the datacenter business. Operating income rose by 124.1 percent to $63.73 billion, and $59.96 billion dropped to the bottom line, up 125.9 percent. Net income was 62 percent of revenue, which is a bit leaner than the share for Q4 F2026 and Q1 F2027, which set successive company records. But that said, this is the kind of percentage of sales that public companies shoot for with their gross margins and rarely attain.
The amazing thing that is worth considering its that Nvidia is spending multiple billions of dollars in research and development each quarter, and that drives maybe 35X to 40X that amount in revenues in quarters out into the future. It is a nearly perfect money making machine, and very close to a printing press that prints chips and gathers up printed money in exchange.
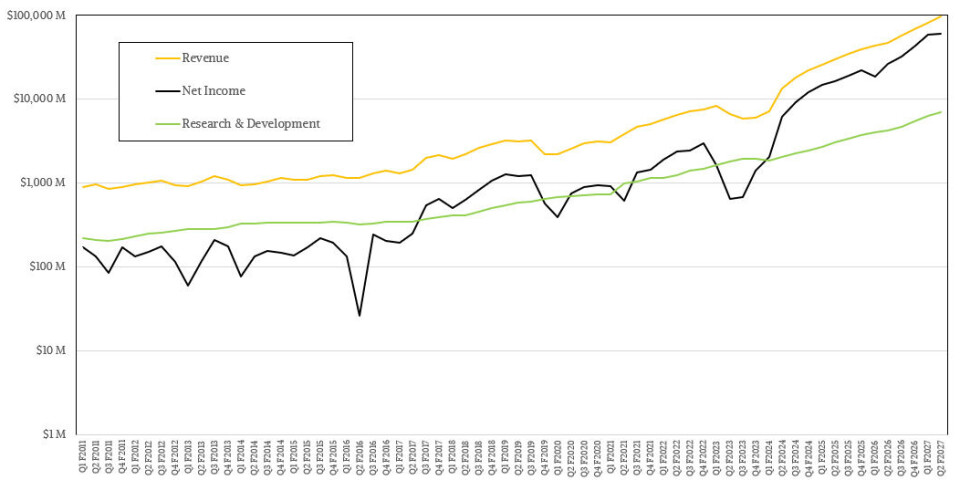
In the current quarter, Nvidia shelled out $7.05 billion in R&D, more than twice what it spent two years ago that is driving Grace-Blackwell and initial Vera-Rubin sales right now.
Imagine if International Business Machines believed in its future and instead of spending $200 billion in share buybacks to appease Wall Street and make its top brass rich (sort of) in the 1990s and 2000s, it took that money and invested it in a future it created. . . .
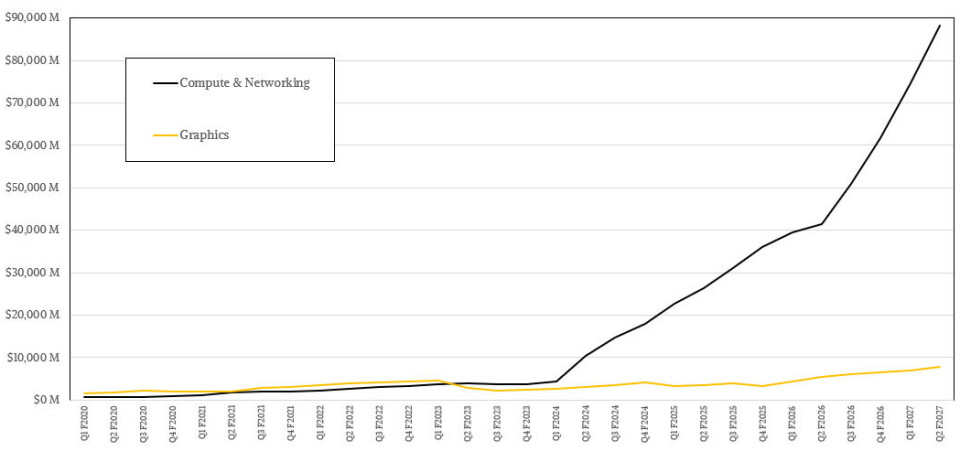
The Compute & Networking group at Nvidia, which sells all of that datacenter stuff and some edge stuff, had $88.3 billion in sales, up 113.6 percent year on year. The Graphics group, which sells PC graphics cards (formerly the Gaming division) as well as workstation GPUs (formerly the Professional Visualization division), brought in $7.92 billion in the quarter, up 46.4 percent. These businesses laid the foundation for the datacenter business, and they are still important to Nvidia, but they are almost noise in the data at this point.
Which is why Nvidia has reclassified its divisions and put all of the automotive electronics plus these graphics businesses as well as its nascent workstation business into a new group called simply Edge Computing.
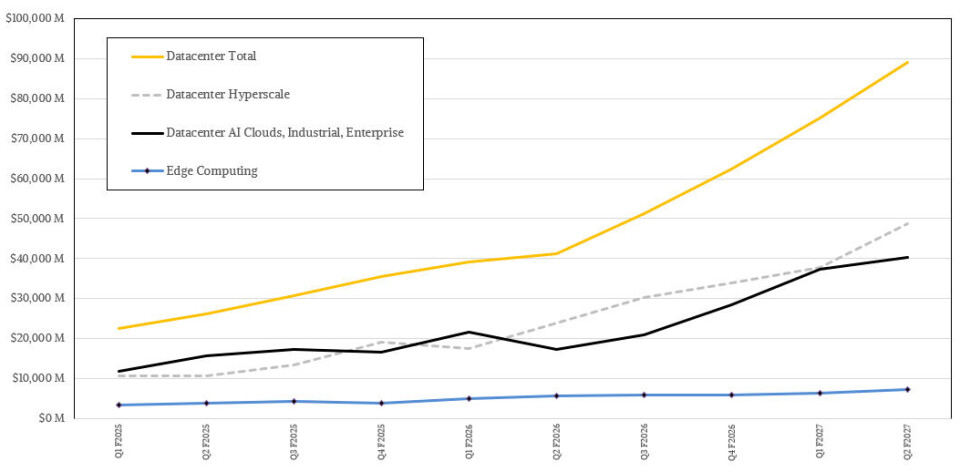
This Edge Computing division is still tiny compared to the Datacenter division, which has been split into hyperscalers (and that includes the big cloud builders) one side and AI Clouds (what we call neoclouds and sovereigns), Industrial, and Enterprise – what Nvidia is calling ACIE as a collective.
The hyperscale portion of the datacenter business had $48.71 billion in sales in Q2 F2027, up 104 percent year on year, while the ACIE had sales of $40.31 billion, up 134.2 percent. I strongly suspect that the neoclouds and a few sovereigns and quite a few HPC/AI centers – which means all formerly HPC-only national labs – are responsible for the bulk of revenues in ACIE.
That brings us to the further drilldown into the datacenter business, which involves some spreadsheet witchcraft based on hints that Nvidia gave about how the compute and networking businesses were doing individually. These numbers used to be given explicitly, and now they are not. Kress said networking was about $15 billion and compute was about $60 billion in Q1 F2027 and luckily we can use that and sequential and annual growth to case it out a bit.
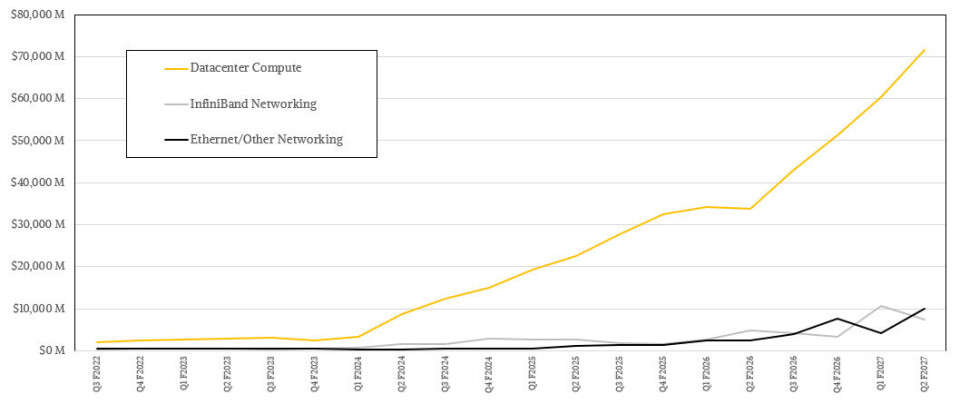
In my model, datacenter compute is up 111.5 percent to $71.57 billion in Q2 F2027, and networking was up 140.7 percent to $17.45 billion. My model also shows Quantum-X InfiniBand sales up 58.9 percent to just a tad under $7.5 billion. That leaves just under $10 billion for Ethernet and NVSwitch components. I reckon that Ethernet revenues drove $5.46 billion of that, and NVSwitch was $4.5 billion in the remainder.
The neat thing is that networking represented 19.7 percent of datacenter sales in Q1 F2027 and 19.6 percent in Q2 F2027. This is twice the rate of networking that clouds and hyperscalers like, but in a rackscale system with NUMA links between GPUs or XPUs, you have to spend twice as much on networking because you are not just scaling out individual nodes. You are trying to make a giant virtual GPU out of dozens of real and smaller GPUs.
